The question looks technical at first. In truth it is strategic – and it decides whether an entire industry has a future. The German automotive supplier landscape is at a turning point: the core business is shrinking, call-offs fluctuate, margins erode. At the same time, new markets are emerging that value precisely what suppliers have perfected over decades – precision, scale and process reliability.
The strategic consequence: – diversification is not a trend but a necessity.
Almost 80 % of German suppliers are actively working on new business areas
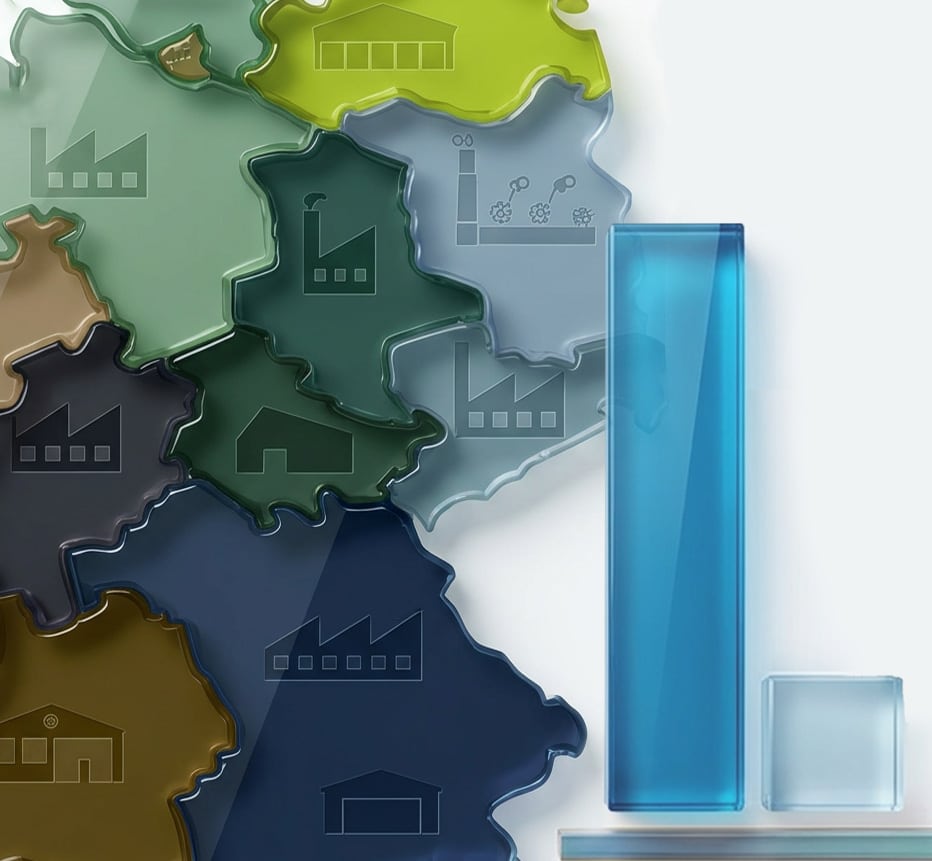
The situation: The business model is losing its stability. For decades the automotive industry set a reliable rhythm. Today it is a risk factor, and the reasons are plain to see.
Opportunities: Spreading risk, higher margins in niche markets, independence from OEM call-off swings.
The competence matrix
The key: Before companies jump into new markets, they have to understand what they are genuinely good at. The competence matrix is not a theoretical instrument but a strategic mirror.
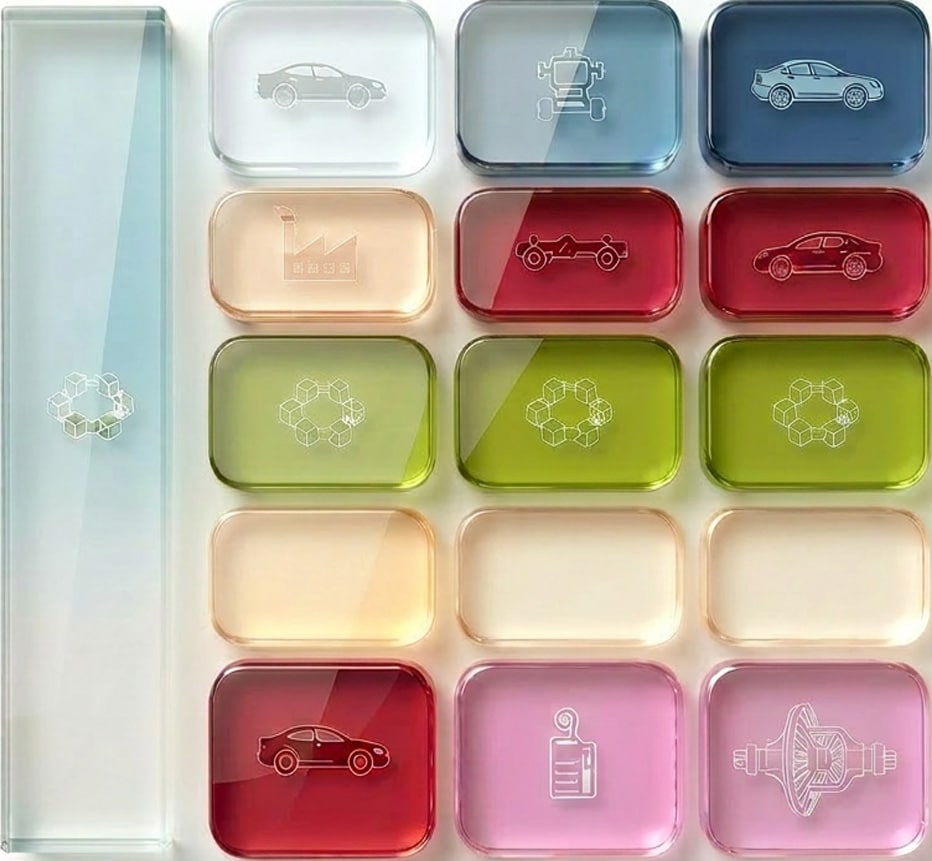
Identifying white spaces: Where do the existing machines and material expertise fit? White spaces appear wherever existing capabilities meet new demand without large investment being necessary.
Make or buy: grow organically or acquire
The route: Entering new markets can happen in two ways in principle: through organic growth or through acquisition.
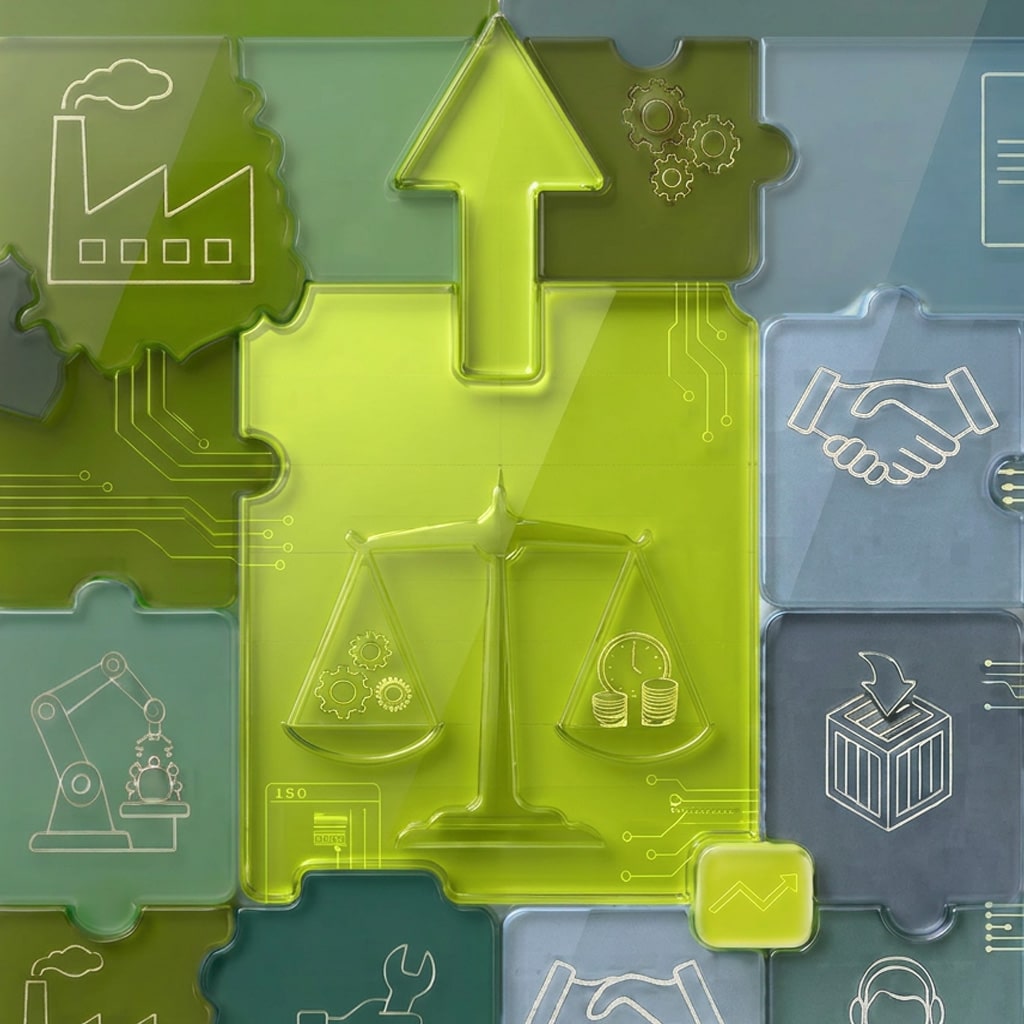
Make-or-buy decisions ultimately depend on the distance between a company’s competences today and the requirements of the target market. The greater that distance, the more an acquisition may make sense; where the distance is small, building organically is frequently the better strategy.
The markets where precision and process reliability are needed today
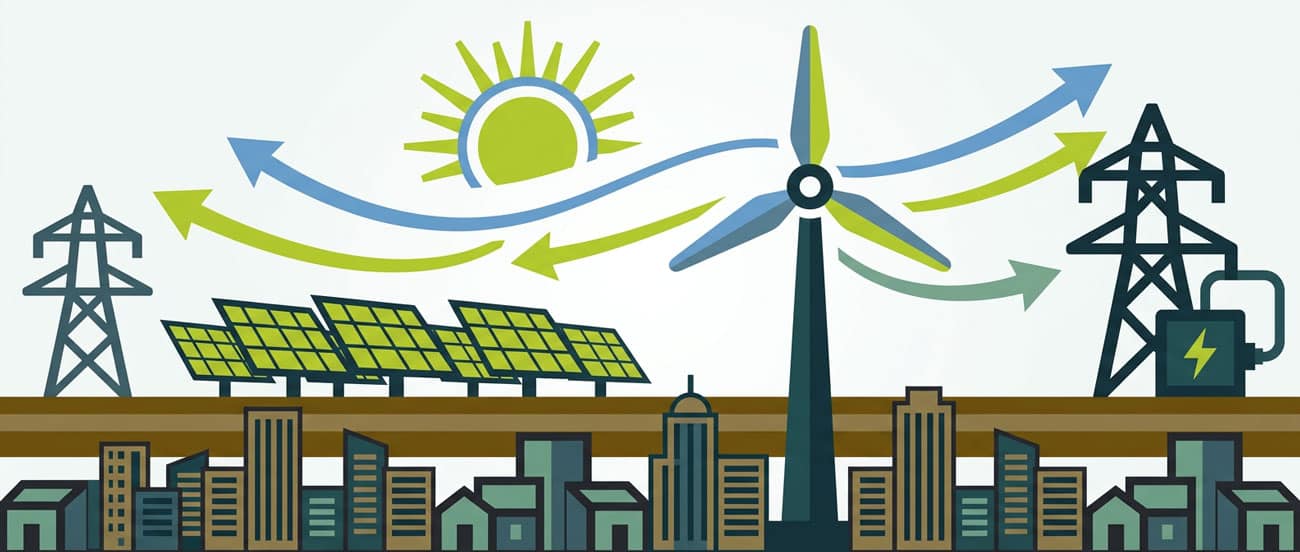
Energy infrastructure – the industrial upturn
Europe is investing heavily in hydrogen, grid expansion and heat pumps. Demand for metal precision components is rising fast:
The market is growing at double-digit rates – and it needs exactly what suppliers can deliver.
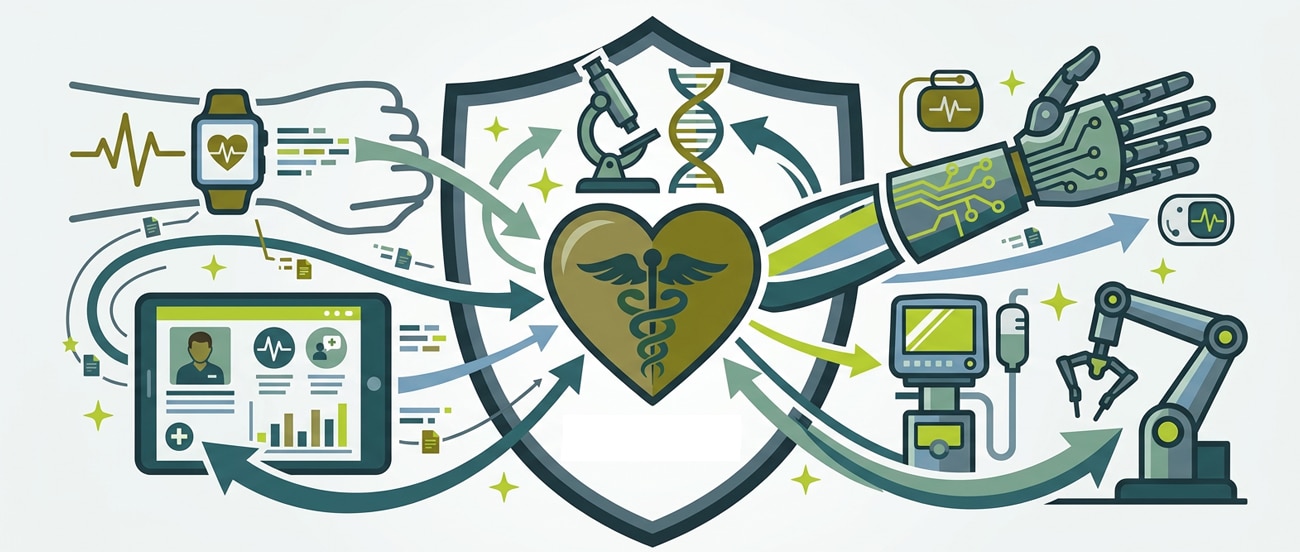
Medical technology – high demands, stable margins
The industry has grown continuously for years. It demands:
Quality standards here are similar to IATF 16949, but the approval routes differ. For many suppliers, medtech is the most natural step outside the automotive world.
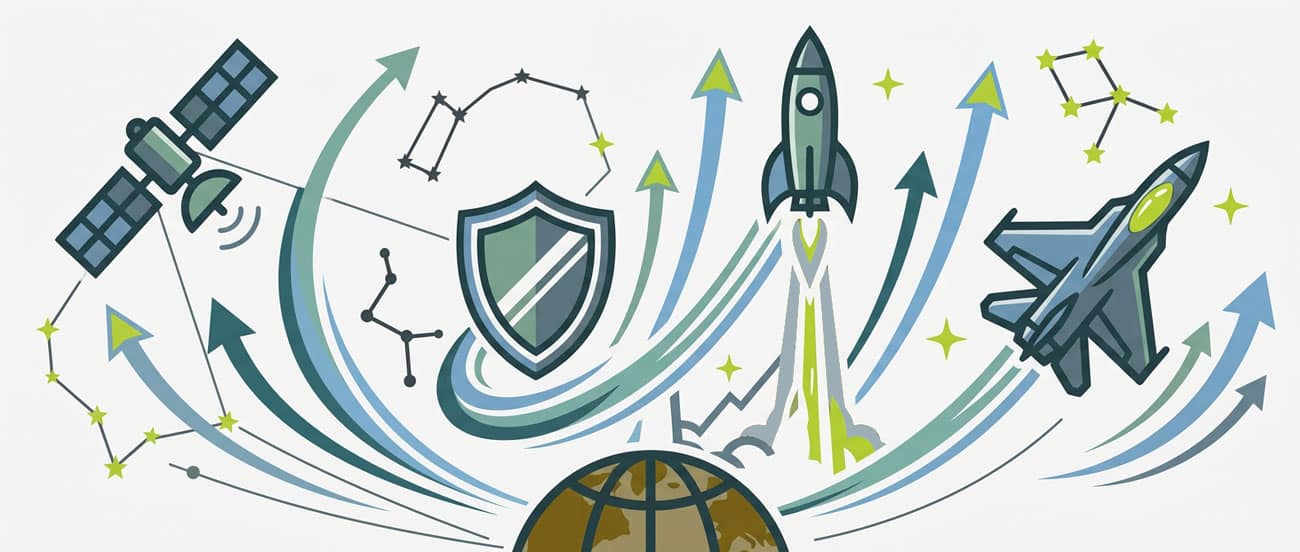
Defence & aerospace – the shift in security policy
Budgets are rising, and so is demand for high-reliability components. Current studies suggest around a quarter of suppliers are already building defence business. The shift in security policy has created substantial demand. Aerospace and defence are demanding sectors – but they reward quality and reliability with stable prices.
New markets call for new ways of thinking
- Diversification is not a project. It is a strategic realignment.
- Diversification does not succeed as a lone management decision. It takes the strength of the whole organisation – it is about people.
- The question is no longer whether suppliers should diversify, but how consistently they do it.
- Companies that act now have an advantage: they can carry their automotive strengths into markets that value precision and reliability just as highly, but pay better for them.
Efficiency, cycle discipline and the zero-defect mindset of the automotive world are an advantage when they are applied in the right place.
The future belongs to those who rethink their competences without losing their identity
Seeing opportunity everywhere is not a strategy
Not every market is a good market, and diversification is no walk in the park. The biggest stumbling blocks are long certification phases (MDR, EN standards), high start-up costs, the danger of spreading yourself too thin, and underestimated sales effort. Seeking professional support is not a sign of weakness but of maturity. Courage is not loud. Courage means taking the right decisions in good time.